A 4-point inspection checks the condition of four major systems in your home so an insurer can decide whether to cover it, while a wind mitigation inspection documents the features that help your home resist hurricane winds. In Florida, the first often affects whether you can get or keep a policy, and the second can affect what you pay.
Both inspections come up a lot for Volusia County homeowners, especially with older homes, home purchases and policy renewals. Here is what each one covers and where your roof fits in.
What a 4-Point Inspection Looks At
The name comes from the four systems the inspector reviews:
- Roof: Age, material, overall condition and signs of leaks or damage.
- Electrical: Panel type, wiring type and any hazards.
- Plumbing: Pipe materials, water heater and visible leaks.
- HVAC: Heating and cooling equipment, age and condition.
Insurers commonly ask for a 4-point inspection on older homes, though the age that triggers it and what they will accept varies from company to company. The inspector usually uses a standard form, takes photos and notes anything that may concern the insurer.
The roof often gets the most attention. An insurer may want to know how many years of useful life the roof has left. If it is near the end of its life or shows damage, some insurers may require repair or replacement before writing or renewing a policy.
What a Wind Mitigation Inspection Looks At
A wind mitigation inspection focuses on construction features that reduce wind damage. Florida uses a standard form for this inspection, and it typically covers items such as:
- Roof covering type and whether it meets current code
- How the roof deck is attached to the framing
- How the roof is connected to the walls, such as toe nails, clips or straps
- Roof shape, since hip roofs tend to perform better than gable roofs in wind
- Whether there is a secondary water barrier
- Opening protection, such as impact windows or shutters
Florida law requires insurers to offer discounts or credits for qualifying wind-resistant features. The size of those credits and how they are applied depend on your insurer, so the same report can mean different savings for different policies.
How a New Roof Can Affect Both Inspections
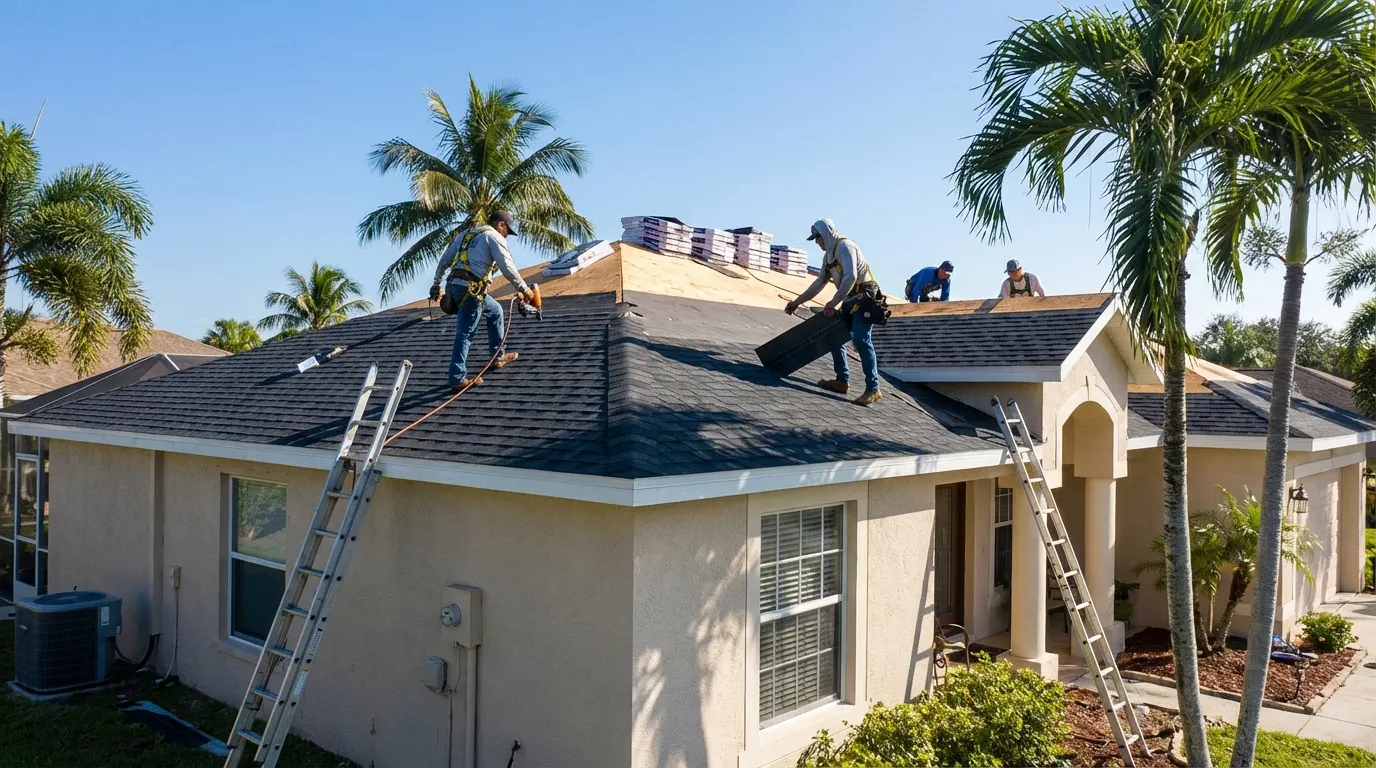
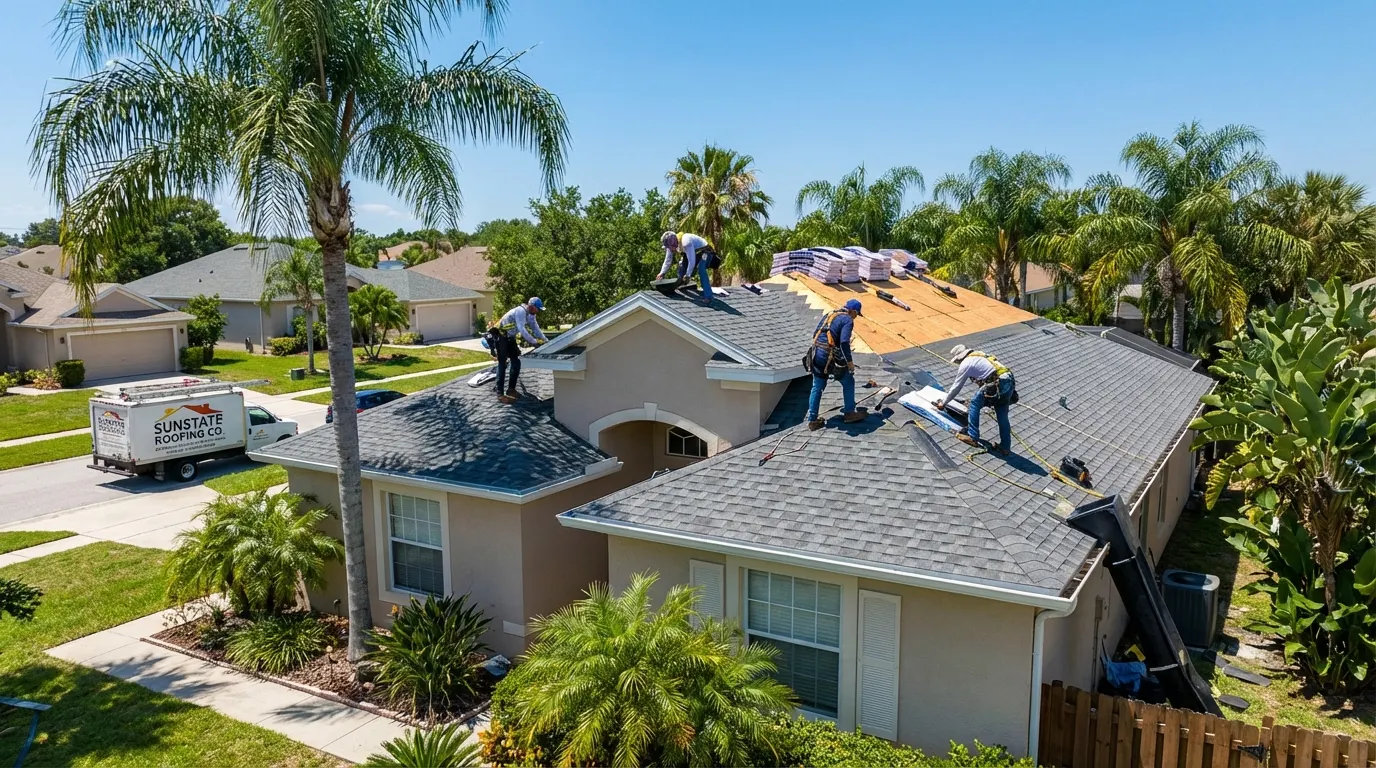
Replacing your roof can change both reports. On a 4-point, a new roof generally answers the insurer's main questions about age and condition. On a wind mitigation inspection, a reroof is a chance to add or document features like a secondary water barrier and improved deck nailing, which may earn credits.
A few practical tips:
- Keep your permit, final inspection record and product information after a reroof
- Ask your roofer what wind features were installed so they can be documented
- Schedule a new wind mitigation inspection after the work is complete
- Send the updated report to your insurer or agent
Timing and Home Purchases
If you are buying a home in Port Orange, Deltona or elsewhere in Volusia County, your insurer may ask for these inspections before closing. Finding out early about an aging roof gives you more time to plan repairs or replacement instead of scrambling at the last minute.
The My Safe Florida Home program has offered free wind mitigation inspections and grants for certain improvements to eligible homeowners. Funding and eligibility change, so check the current details at mysafeflhome.com.
How We Can Help
Coastal Home Creations & Roofing does not replace your inspector, but we can help you get ready. We offer free roof inspections so you know your roof's condition before an insurance inspection, and we handle roof repair and replacement when it is needed. Bill Edwards holds Florida Roofing Contractor license CCC1335297. Contact us or call 386-785-3651 to set up a visit.
FAQ
Who performs 4-point and wind mitigation inspections?
They are performed by qualified professionals such as licensed home inspectors and certain contractors, engineers and architects. Your insurer can tell you whose reports it accepts.
Is a wind mitigation inspection required?
It is usually optional, but it is how you document features that may qualify for insurance credits. Ask your insurer or agent how it applies to your policy.
Will a new roof guarantee lower premiums?
Not necessarily. A new roof can improve your inspection results, but premiums depend on many factors and each insurer's rules. Check with your insurer about your specific situation.
Written by the Coastal Home Creations team: third-generation builders licensed in Florida (GC CGC1506738, Roofing CCC1335297). General information only; for your specific home, call 386-785-3651.